
Financing ADU project construction is one of the most important — and most misunderstood — steps for California homeowners planning to build an accessory dwelling unit (ADU), a secondary residential unit built on the same lot as a primary home. Whether you’re picturing a detached backyard cottage, a garage conversion, an attached addition, or a junior ADU carved out of existing space, the way you fund the build often determines whether your project breaks ground on schedule or stalls indefinitely.
According to the U.S. Census Bureau, California leads the nation in ADU permit applications, with tens of thousands filed every year. As a result, homeowners across Orange County, Los Angeles County, and Riverside County increasingly need clear, numbers-based answers — not just a list of loan names, but a real understanding of how lenders calculate what you can borrow. This guide covers both: every major financing path available in 2024, plus the exact math lenders use to decide your loan amount.
Financing ADU Project Costs in Southern California
Simply put, financing your ADU project means securing enough capital to cover design, permitting, and construction before and during the build. Most homeowners do not pay entirely out of pocket. Instead, they lean on financial products tied to their home’s equity, their income, or the ADU’s projected rental value.
In Southern California, total ADU construction costs typically range from $100,000 to $300,000, depending on the unit type and size. Homeowners in the Orange County market often review options like ADU loans in Orange County early in the planning process, since local property values directly affect how much equity-based financing is available. Consequently, having a clear funding plan before you talk to a contractor isn’t optional — it’s foundational to your entire timeline.
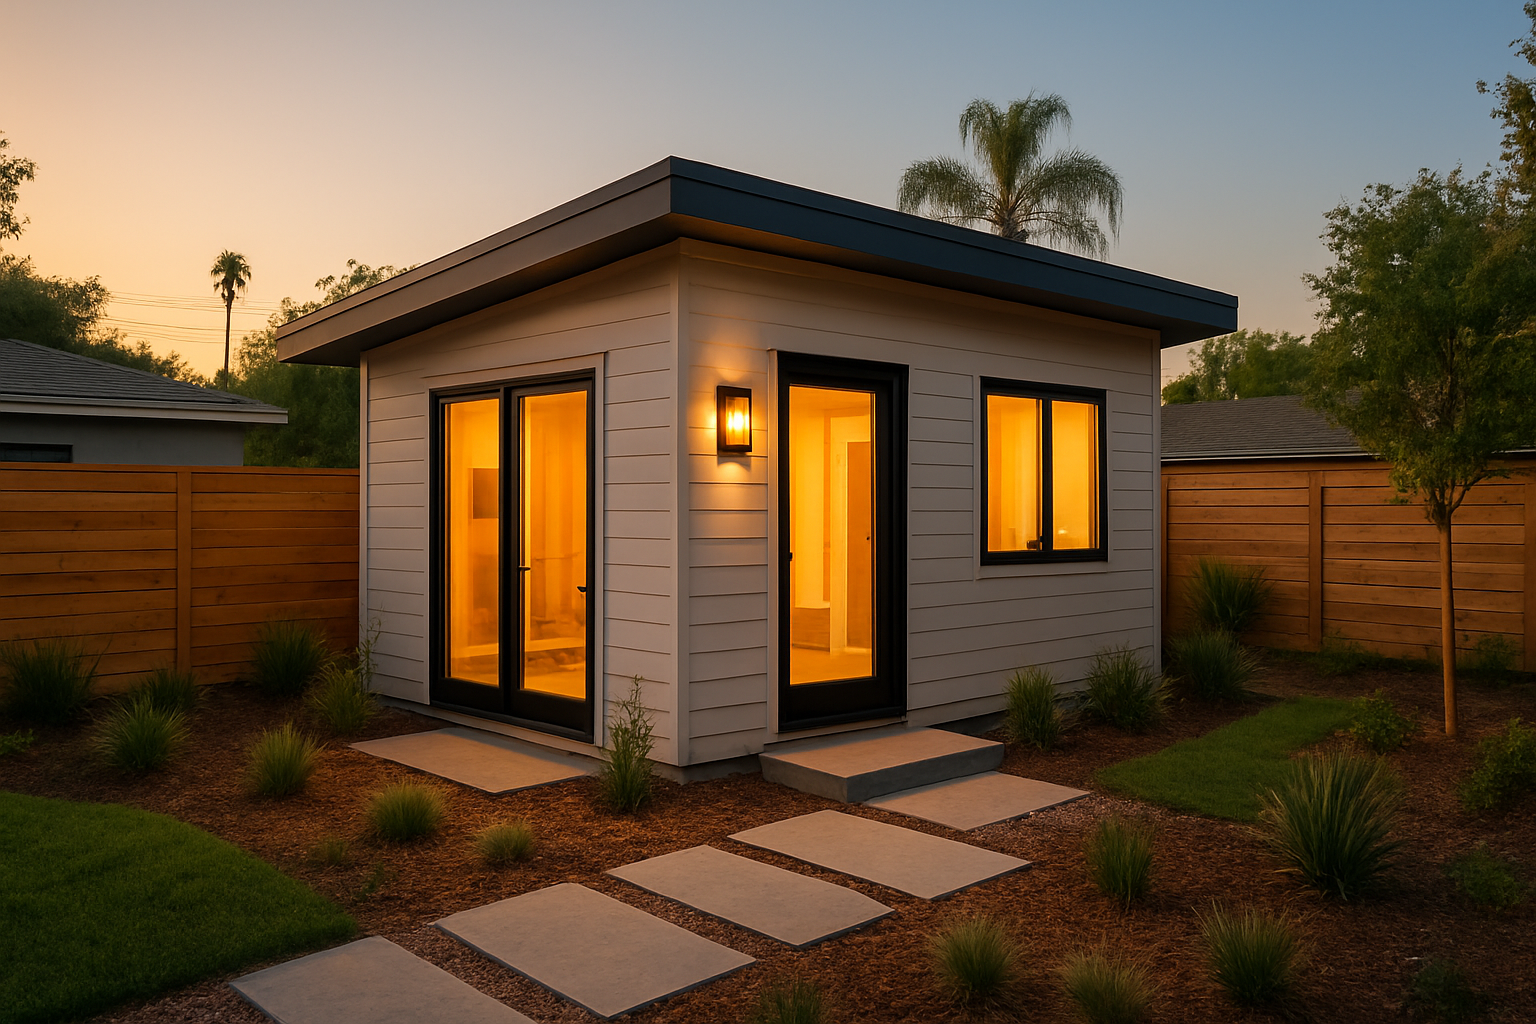
A completed detached ADU in Southern California — the kind of project that becomes achievable with the right financing strategy in place.
How to Calculate Your ADU Loan Amount
Before comparing loan products, it helps enormously to understand the actual math lenders use to determine your borrowing power. Four ratios drive nearly every ADU lending decision: loan-to-value (LTV), loan-to-cost (LTC), debt-to-income (DTI), and debt service coverage ratio (DSCR). Below, each is explained with a real formula so you can estimate your own numbers before ever applying.
Loan-to-Value (LTV) and Combined LTV Explained
LTV compares a loan amount to your home’s appraised value. Combined loan-to-value (CLTV) goes a step further by adding your existing mortgage balance into the equation — which matters because almost every equity-based ADU loan is a second lien behind your primary mortgage. Most lenders cap CLTV between 80% and 90% for HELOCs and home equity loans used to fund an ADU.
Formula: Available equity = (Home value × maximum CLTV%) − existing mortgage balance
Example: A home worth $850,000 with an existing mortgage balance of $400,000, at an 85% max CLTV, unlocks ($850,000 × 0.85) − $400,000 = $322,500 in available financing.
Loan-to-Cost (LTC) for Construction Loans
Unlike LTV, which looks at home value, LTC compares your loan amount to the total project cost — design, permits, and construction combined. This is the ratio construction lenders rely on most heavily, since the home itself isn’t finished yet.
Formula: LTC = Loan amount ÷ total project cost
Example: On a $220,000 ADU build, a lender offering 90% LTC would finance up to $198,000, leaving the homeowner responsible for the remaining $22,000 (10%) in cash or a secondary source.
Debt Service Coverage Ratio (DSCR) for ADU Rental Income
Some ADU lenders, particularly those offering rental-income-based programs, evaluate debt service coverage ratio (DSCR) instead of — or in addition to — your personal income. DSCR measures whether the ADU’s projected rent can cover its own loan payment.
Formula: DSCR = Projected monthly rental income ÷ monthly loan payment
Example: An ADU expected to rent for $2,200/month against a $1,600/month payment produces a DSCR of 1.375 — comfortably above the 1.0 to 1.25 minimum most lenders require.
Finally, lenders also check debt-to-income (DTI) ratio — your total monthly debt payments, including the new loan, divided by gross monthly income. Most programs cap DTI between 43% and 50%. In contrast to DSCR, which looks at the ADU alone, DTI evaluates your entire financial picture. For a plain-language breakdown of how equity lines factor into this math, the Consumer Financial Protection Bureau offers a helpful consumer-facing explanation.
Sample ADU Financing Calculation Walkthrough
Let’s put every formula above together into one realistic scenario, since seeing the full math side-by-side makes financing your ADU project far less abstract.
Home value: $850,000 | Existing mortgage: $400,000 | Project cost: $220,000
1. HELOC at 85% CLTV unlocks $322,500 in available equity — more than enough to cover the $220,000 build.
2. Projected ADU rent of $2,200/month against an estimated $1,600 monthly HELOC payment yields a DSCR of 1.375 — strong enough to satisfy most rental-income underwriting.
3. Because rental income exceeds the payment by $600/month, the homeowner’s effective out-of-pocket housing cost decreases once the ADU is occupied.
Of course, every property is different. However, running your own numbers through these same four formulas — LTV, LTC, DSCR, and DTI — before contacting a lender will save you weeks of back-and-forth during underwriting.
Top Loan Options for Funding Your ADU Build
Fortunately, homeowners today have more loan products available than ever before. Each carries its own terms, benefits, and eligibility rules. Below are the financing tools used most often for ADU construction in California, now paired with the calculation context from above.
Home Equity Line of Credit (HELOC)
A HELOC is a revolving credit line secured by your home’s equity. It works similarly to a credit card: you draw funds as needed during construction and pay interest only on what you’ve actually used. This flexibility makes it especially popular for ADU builds, where expenses are staged over several months rather than paid all at once.
To qualify, most lenders require 15% to 20% equity remaining after the line is opened — which is exactly why the CLTV formula above matters so much. Additionally, a credit score of 680 or higher typically yields the most competitive rates. For more detail, visit the ADU financing options guide at theadupro.com.
Home Equity Loan
Unlike a HELOC, a home equity loan provides a lump sum at a fixed interest rate. This suits homeowners who already have a firm project budget and prefer predictable monthly payments. Because the rate is fixed, you’re protected from rising interest rates throughout repayment.
Home equity loans generally offer terms of 5 to 30 years, so monthly payments can be structured to stay manageable even on larger ADU builds. Some homeowners also compare specialized renovation lenders such as RenoFi renovation loans, which calculate borrowing power against your home’s after-construction value rather than its current value — often unlocking more funding than a standard home equity loan.
Cash-Out Refinance
A cash-out refinance replaces your existing mortgage with a new, larger loan. The difference between the two amounts is paid to you in cash, which you then use to fund your ADU. This option works best when current rates are equal to or lower than your existing mortgage rate.
However, if rates have risen significantly since you bought your home, a cash-out refinance may increase your overall monthly costs. Therefore, always run both the LTV formula and a full payment comparison before choosing this route.
ADU Construction Loan
A construction loan is a short-term loan built specifically to cover building costs. Funds are released in stages — called draws — as each phase of construction wraps up. Once the ADU is finished, the loan either converts to a permanent mortgage or is paid off through a refinance.
Construction loans require a detailed project plan and contractor bids upfront, since lenders apply the LTC formula covered earlier to verify the project is viable before committing funds. Learn more about how to receive your ADU funding through a structured draw process.
California Grants and Assistance Programs Worth Knowing
In addition to traditional loans, California has introduced grant programs aimed squarely at reducing the upfront cost of ADU development. The CalHFA ADU Grant Program has offered eligible homeowners up to $40,000 to cover pre-development and non-recurring closing costs. While funding availability shifts with each cycle, it represents a meaningful way to lower your out-of-pocket burden before construction even starts.
Similarly, several municipalities within Los Angeles County and Orange County have launched their own incentive programs. Homeowners in the Inland Empire have local options too — the ADU loans in Redlands page and the ADU financing options in Ontario page both outline programs tailored to those specific markets. It’s worth checking with your city’s housing department in addition to state-level resources.
Reviewing loan documents and construction plans together helps homeowners make confident financing decisions for their ADU build.
Fannie Mae Programs That Support ADU Funding
Fannie Mae has expanded its lending guidelines to better accommodate ADU financing. Its HomeStyle Renovation loan, for example, lets homeowners bundle ADU construction costs into a single mortgage. This is particularly useful for buyers purchasing a property with the intent to build an ADU right away.
Furthermore, Fannie Mae now allows lenders to count projected ADU rental income when qualifying borrowers for certain loan products — essentially applying the same DSCR logic described earlier at the underwriting level. This makes it significantly easier for homeowners to qualify for the loan amount they actually need.
How to Finance Your ADU Project Step by Step
Following a structured approach helps you avoid delays and secure the right funding product for your situation. Here is a proven six-step process:
- Determine your ADU budget. Get a detailed cost estimate from a licensed contractor, including design, permitting, construction, and a 10% to 15% contingency buffer for surprises.
- Assess your equity and financial profile. Review your home equity, credit score, and debt-to-income ratio, then run the LTV and LTC formulas above to estimate your borrowing power.
- Research and compare loan products. Compare HELOCs, home equity loans, cash-out refinances, and construction loans across multiple lenders, focusing on rates, draw terms, and closing costs.
- Check for grants and assistance programs. Visit CalHFA’s website and your local county housing authority to identify available grants or low-interest ADU programs before you apply.
- Submit your loan application. Gather proof of income, tax returns, a property appraisal, and your ADU construction plans, then submit a complete application to begin underwriting.
- Close on financing and begin construction. Once approved, coordinate with your contractor to release funds according to the draw schedule and officially start your build.
Why ADU Financing Is a Smart Long-Term Investment
Beyond the construction itself, financing an ADU is a wealth-building strategy. Research from the Urban Institute indicates that ADUs can increase property values by 20% to 30% in many California markets. In addition, rental income from a well-positioned ADU in Southern California can range from $1,500 to $3,000 or more per month, depending on location and unit quality.
Consequently, many homeowners find that ADU rental income covers — or even exceeds — the monthly loan payment, exactly as demonstrated in the DSCR example earlier. This effectively makes the ADU self-financing over time. For a complete regional breakdown of every option covered here, see the complete Southern California ADU financing guide.
theadupro.com has helped hundreds of homeowners across Orange County, Los Angeles County, and Riverside County navigate both the construction and financing sides of ADU development. Their easy-to-finance approach is designed to reduce barriers and simplify the funding process from day one. Author: The ADU Pro team. Last updated: 2026-06-26.
Southern California neighborhoods increasingly feature ADUs funded through a variety of smart financing approaches.
Common Mistakes to Avoid When Securing ADU Funding
Even well-prepared homeowners can stumble during the financing process. Here are the pitfalls to avoid:
- Underestimating total project costs. Always include permitting fees, utility connections, and landscaping in your budget — not just hard construction costs.
- Applying for only one loan product. Comparing multiple lenders and loan types, and running your own LTV/LTC math first, can save thousands in interest over the life of the loan.
- Ignoring the draw schedule. Misaligned draw schedules between your lender and contractor can cause costly construction delays.
- Skipping the grant search. Many homeowners miss out on thousands in free funding simply because they didn’t research available programs before applying for a loan.
- Ignoring DSCR before setting rent expectations. Overestimating achievable rent can throw off your entire qualification math — research comparable rents in your area first.
For a deeper look at every funding path, explore the ADU financing resources section at theadupro.com, covering everything from grant eligibility to lender comparisons.
Frequently Asked Questions About Financing Your ADU Project
What does financing your ADU project typically cost in California?
Financing your ADU project in California typically involves total project costs ranging from $100,000 to $300,000, depending on ADU type, size, and location. Detached ADUs tend to cost more than garage conversions or junior ADUs. Your financing costs — interest and fees — will vary based on the loan product you choose.
What is the best loan option for an ADU build?
The best option depends on your equity, credit score, and timeline. HELOCs and home equity loans are popular for homeowners with significant equity. Construction loans and cash-out refinances work well for larger projects or buyers purchasing and building at the same time.
Can I use a HELOC to fund an ADU?
Yes. A HELOC is one of the most flexible ways to fund an ADU. It lets you draw funds as needed during construction, which helps manage cash flow effectively. Most lenders require 15% to 20% remaining equity after the line is opened.
How do I calculate how much I can borrow for my ADU?
Lenders typically calculate your available loan amount using combined loan-to-value (CLTV) or loan-to-cost (LTC), depending on the loan type. For equity-based loans, multiply your home’s value by the lender’s maximum CLTV (often 80% to 90%), then subtract your existing mortgage balance. For construction loans, lenders apply an LTC ratio, usually 80% to 90% of total project cost.
What is loan-to-value (LTV) and why does it matter for ADU financing?
LTV compares your loan amount to your home’s appraised value, while combined loan-to-value (CLTV) also factors in your existing mortgage. Lenders use LTV/CLTV to determine how much equity-based financing you qualify for, typically capping it between 80% and 90% for ADU-focused HELOCs and home equity loans.
What is DSCR and how does it affect ADU loan approval?
Debt Service Coverage Ratio (DSCR) divides your projected monthly ADU rental income by your total monthly debt payment on the new loan. Many lenders require a DSCR of 1.0 to 1.25 or higher, meaning the rental income should fully cover — or exceed — the loan payment before approving financing.
Does California offer grants for ADU construction?
Yes. The CalHFA ADU Grant Program has offered up to $40,000 to eligible homeowners for pre-development and non-recurring closing costs. Availability depends on funding cycles, so check CalHFA’s website for current program status before applying.
How does a cash-out refinance work for ADU financing?
A cash-out refinance replaces your existing mortgage with a larger loan, and you receive the difference in cash to fund your ADU. This works best when current interest rates are favorable compared to your existing mortgage rate.
What is an ADU construction loan?
An ADU construction loan is a short-term loan that covers building costs during the construction phase. Funds are released in draws as each phase is completed. Once the ADU is finished, the loan typically converts to a permanent mortgage or is paid off through refinancing.
What is loan-to-cost (LTC) and how is it different from LTV?
LTC compares your loan amount to the total cost of the ADU project, while LTV compares the loan to your home’s current appraised value. Construction loans rely on LTC, typically capping funding at 80% to 90% of project cost, whereas HELOCs and home equity loans rely on LTV/CLTV.
Can rental income from my ADU help pay off the loan?
Absolutely. Many homeowners use ADU rental income to offset monthly loan payments. In Southern California, ADUs can generate $1,500 to $3,000 or more per month depending on location and unit quality, which can make the ADU largely self-financing over time.
What credit score do I need to finance an ADU?
Most lenders require a minimum credit score of 620 to 680 for ADU financing. However, better rates and terms are typically available for borrowers with scores of 720 or higher. Improving your credit before applying can significantly reduce your total interest costs.
Is it possible to finance an ADU with no equity?
It is more challenging but not impossible. Some lenders offer personal loans or unsecured home improvement loans that do not require equity. However, these products typically carry higher interest rates, so they should be used as a last resort.
How long does it take to get ADU financing approved?
Approval timelines vary by loan type. HELOCs and home equity loans typically take 2 to 6 weeks. Construction loans may take 4 to 8 weeks due to additional underwriting requirements. Submitting a complete application upfront helps minimize delays.
Does adding an ADU increase my property value?
Yes. Research indicates that adding an ADU can increase property value by 20% to 30% in many California markets, making ADU construction a strong long-term investment that can more than offset the cost of financing over time.
What is a Fannie Mae HomeStyle loan and can it fund an ADU?
The Fannie Mae HomeStyle Renovation loan allows homeowners to finance both a home purchase or refinance and renovation costs in a single loan. It can fund ADU construction when the ADU adds value to the primary property, which is especially useful for buyers who want to build immediately after purchasing.
Conclusion: Making Financing Your ADU Project Work for You
Financing your ADU project requires careful planning, but the tools available to Southern California homeowners today make it more accessible than ever. Whether you choose a HELOC, a home equity loan, a cash-out refinance, or a construction loan, the key is matching the product — and the underlying LTV, LTC, or DSCR math — to your financial profile and project timeline. In addition, taking advantage of California grants and Fannie Mae programs can meaningfully reduce your upfront costs. Above all, partnering with an experienced ADU contractor like theadupro.com ensures your build is managed efficiently, so your investment delivers maximum value from day one. With the right funding strategy, the right numbers, and the right team behind you, financing your ADU project is well within reach.